Short Sale in New Jersey
If you owe more than the home is likely to sell for, a short sale is one way to ask the lender to accept less than a full payoff so the property can be sold. Kevin Hill can also show you what an as-is cash offer would look like, and what the home might bring if it were listed on the open market — so you are not choosing a path in the dark.
Kevin Hill is a licensed New Jersey REALTOR® with Keller Williams Valley Realty and completed the USREO Partners Short Sale Specialist Certification Course on November 8, 2026.
Explore a short sale, an as-is cash offer, and a market listing side by side.
Tell Kevin about the property to compare realistic options.
Compare Your Selling Options
Tell Kevin about the property. He will follow up with a cash-offer figure next to an estimate of what the home could sell for if you listed it on the open market—and, if the loan is underwater, whether a short sale is worth discussing with your lender and attorney.
A short sale is a sale in which the mortgage lender (and any other lienholder who must agree) accepts a payoff that is short of the full balance so the home can close. It is not a gift, a guaranteed approval, or a way to walk away from the loan on your own timetable. The lender has to review a package, and a New Jersey real estate attorney should be involved, as with any home sale in this state.
A short sale may be worth discussing when:
• The expected sale price, after the costs of selling, would not cover what is owed.• You are behind on payments, or you can see that you will fall behind.• You want to try to sell the property in a controlled way rather than wait for a foreclosure sheriff’s sale.• You are prepared to document a hardship and work with your lender, an attorney, and a qualified agent.
A short sale is usually not the first path if you have meaningful equity, can catch up, or can modify the loan. Review those options first, including free foreclosure-prevention counseling through NJHMFA and the resources on the New Jersey Courts foreclosure self-help page.
Who this is for
Homeowners in Bergen County and the rest of North Jersey who are:
• Underwater, or close to it, on a primary residence, an inherited house, or a rental.• In pre-foreclosure or already in a New Jersey foreclosure case, and want to know whether a sale can still be completed before a sheriff’s sale.• Trying to understand a short sale, an as-is cash offer, listing the home if the numbers work, or continuing in foreclosure.
New Jersey House Partners does not give legal, tax, or credit-repair advice. Kevin will talk through the real estate options and work alongside your attorney, lender, and, when tax or credit questions come up, your CPA or a HUD- or NJHMFA-certified housing counselor.
How a short sale compares with foreclosure, a cash offer, and a listing
This is a general comparison, not a prediction of your result. Terms, timing, and proceeds depend on the property, the lender, title, and the contract.
Short sale. The home is sold (listed on the open market, or sometimes to a cash buyer) for an amount the lender agrees to accept, even if that amount is less than the payoff. Closing cannot happen until the lender approves the sale. That review can take weeks or months. You will usually need a hardship explanation and financial documents. Ask your attorney and CPA about any remaining balance, tax reporting, and credit effects before you sign.
Foreclosure. New Jersey is a judicial foreclosure state: the lender has to go through the courts. The process is described below. A foreclosure can end in a sheriff’s sale of the property. It can also affect credit and, if the sale does not cover the debt, can leave a remaining balance the lender may still pursue. A short sale is sometimes completed during a foreclosure case, but that is never guaranteed, and you should not ignore court deadlines while a sale is being discussed.
As-is cash offer. Kevin can present a direct cash offer on the home in its current condition. A cash offer is often lower than a price you might reach with a marketed listing, because the buyer is taking on condition, time, and risk. In a short-sale situation, a cash buyer can still be useful if the offer is one the lender will consider and the timeline is clearer. Review the actual offer, including inspections, fees, and proposed closing date, before you decide. Nothing in a cash offer is a promise to close in a set number of days, skip every inspection, or pay every cost.
Listing on the open market. If a realistic list price, after commissions, transfer taxes, and usual selling costs, would cover the loan and leave you proceeds, listing with Kevin as a New Jersey REALTOR® is often the better way to go. If the math does not work, the same listing process can still be used as the vehicle for a short sale, with the lender’s approval required before closing.
How the process usually works
Every file is different. This is the typical sequence Kevin uses so you know what to expect.
1. A conversation about the numbers and the timeline. Share the property address, what you owe if you know it, any foreclosure notices or court papers, and what you are trying to accomplish. Call or text (201) 214-1349, or use the form on this page.
2. A comparison, in writing, of realistic paths. Kevin looks at comparable sales, condition, and likely selling costs, then puts an as-is cash offer next to what the home could reasonably sell for if listed, and whether a short sale appears necessary. This comparison is not a formal appraisal and is not a lender decision.
3. Your attorney, your lender, and counseling. If a short sale is on the table, you should have a New Jersey real estate attorney. If you are behind on payments, consider free counseling through NJHMFA and, if a foreclosure complaint has been served, the information on the New Jersey Courts foreclosure page, including mediation. Kevin coordinates with your attorney; he does not replace one.
4. Marketing or a cash buyer, then a contract. The home may be listed, or a cash offer may be written, depending on what is most likely to be acceptable to the lender and workable for you. In New Jersey, the contract is subject to attorney review.
5. The short-sale package and lender review. The buyer’s offer, your hardship documentation, and supporting financials go to the lender (and any other required lienholder). Approval is the lender’s decision. It can be delayed, reduced, or declined.
6. Closing, if the lender approves and title is clear. A New Jersey attorney handles the closing. Read every condition in the approval letter, including any request that you contribute funds, any statement about a remaining balance, and the expiration date of the approval.
If at any point the better path is a loan modification, a catch-up plan, a listing with equity, or a cash sale that is not a short sale, Kevin will say so.
New Jersey specifics
New Jersey foreclosures are judicial and go through the Superior Court. The Office of Foreclosure and Superior Court General Equity judges handle the process. The following are general descriptions from the New Jersey Courts foreclosure self-help page, not a timeline for your case.
• Before filing, the lender must send a Notice of Intent to Foreclose. From receipt, the homeowner generally has 30 days to cure the default or make other arrangements. The notice also includes information about selling or transferring title, the right to an attorney, and foreclosure mediation.• After a foreclosure complaint is served, the homeowner generally has 35 days to file an answer if they intend to contest the case. Uncontested matters stay with the Office of Foreclosure; contested matters go to a Superior Court judge in the county where the property is located.• If the case proceeds to final judgment, the court may issue a writ of execution. The county sheriff then has 150 days from that writ to auction the property, subject to stays. After a sale, a short redemption period may apply, as explained by the courts.• Free foreclosure mediation is available if you meet the eligibility rules. Lenders can still continue the case during mediation, so it is not a substitute for watching your dates.• Watch for foreclosure-rescue scams. New Jersey Courts recommends staying in contact with your lender or servicer and using a HUD- or NJHMFA-certified housing counselor. Kevin is a real estate agent, not a foreclosure-rescue company.
Because this court process often takes many months from the first notice to a sheriff’s sale, some homeowners have a window in which to complete a short sale or another sale before an auction. That window is not a promise. Court dates still matter, and only your attorney can advise you about your case.
Bergen County sheriff’s sale scheduling, and timing in Essex, Passaic, and nearby counties, varies. Do not rely on a neighbor’s timeline.
Credit and taxes (general only — ask your own advisors). A short sale and a foreclosure can both appear on a credit report and affect future borrowing. Neither is a guaranteed way to save your credit. How either is reported, and for how long, depends on the account and current credit-reporting rules. A housing counselor or attorney is the right place for questions about your credit.
If a lender forgives or writes off part of the debt, that forgiven amount may be reported to you as income. Whether it is taxable, and whether an exception applies, is a tax question. New Jersey House Partners cannot tell you how the IRS or State of New Jersey will treat your file. Talk to a CPA or tax attorney, and to your real estate attorney, before relying on a short sale or foreclosure to solve a tax or deficiency issue.
Kevin’s USREO Partners certification
Kevin Hill completed the USREO Partners Short Sale Specialist Certification Course on November 8, 2026. The course was hosted by USREO Partners at the Housing Intelligence Conference in Fort Worth, Texas, in November 2026. The certificate of completion is pictured below (instructor: Sharon Bartlett).
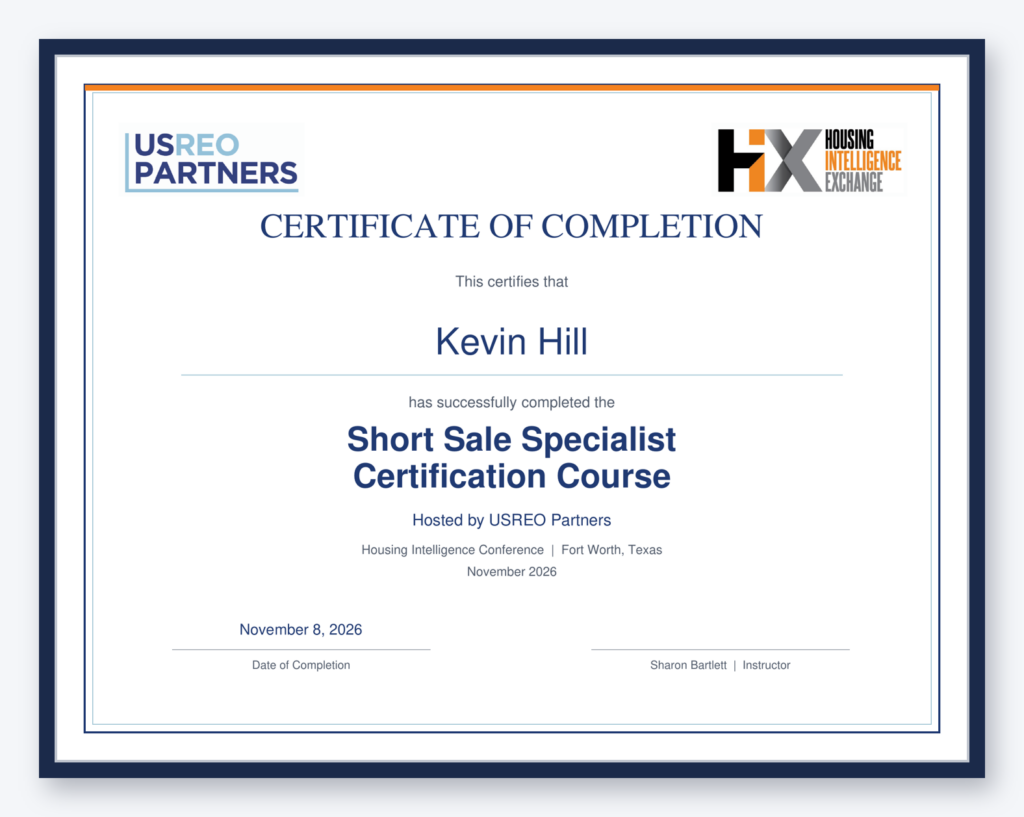
This certification means Kevin has completed that specialist course. It is not a guarantee that a lender will approve a short sale, and it is not a law license. He also holds a Seniors Real Estate Specialist (SRES) designation, has a background as a residential appraiser, and has worked with broker price opinions, REO, and distressed property sales. New Jersey real estate license #0894817.
What to do next
Call or text Kevin at (201) 214-1349, email Kevin@NJHousePartners.com, or send the form on this page. If you already have a foreclosure complaint, a sheriff’s sale date, or a notice of intent, say so in your message so the conversation can start in the right place.
If you need free counseling rather than a sales conversation, start with NJHMFA foreclosure prevention at https://www.nj.gov/dca/hmfa/ and New Jersey Courts foreclosure self-help at https://www.njcourts.gov/self-help/foreclosure.
Frequently asked questions
What is a short sale in New Jersey? A sale in which your lender agrees to accept less than the full mortgage payoff so the home can close. A New Jersey attorney should handle the contract and closing, and the lender—not the agent—decides whether to approve the sale.
Can I do a short sale if a foreclosure has already been filed? Sometimes, if the lender will still consider an offer and there is enough time before a sheriff’s sale. You must still meet court deadlines. Ask your attorney about your case, and do not assume a pending short sale automatically stops the foreclosure.
How long does a short sale take? It varies. Putting the home under contract is only one part. Lender review, title work, and New Jersey attorney review add time. Some files move in weeks; many take longer. Anyone who promises a set closing date up front is guessing.
Will a short sale cost me money at closing? Not always, but it can. A lender may ask for a contribution, and you may still have usual costs depending on the approval letter and contract. Ask for a written estimate before you agree.
Is a cash offer better than listing the home as a short sale? It depends on the offer, likely list price, timeline, and what the lender will accept. Kevin puts an as-is cash offer next to a realistic listing outcome so you can compare. A cash offer is often lower than a marketed price; sometimes simplicity and timing still make it the better net decision.
What if I have equity? Then a short sale may be unnecessary. Listing the home, or comparing a cash offer with a listing, is usually the starting point.
Will this ruin my credit or create a tax bill? It can affect credit, and forgiven debt may have tax consequences. The details are personal. Speak with a CPA or tax attorney and your real estate attorney. Kevin will not guess at your tax or credit outcome.
Do I need an attorney? Yes, you should have a New Jersey real estate attorney for the sale. If a foreclosure case is pending, you should also get legal advice about that case. New Jersey Courts explains the process but cannot give you legal advice.
Important information
New Jersey House Partners is a real estate brand of Kevin Hill, a licensed New Jersey REALTOR® with Keller Williams Valley Realty, 123 Tice Blvd, Suite 100, Woodcliff Lake, NJ 07677. NJ License #0894817. Equal Housing Opportunity.
This page is general information, not legal, tax, or financial advice, and not a promise of lender approval, a closing date, a credit result, or a particular net proceeds figure.