By Kevin Hill, REALTOR® | Keller Williams Valley Realty | NJ House Partners
Market data reviewed November 11, 2026. Market comparisons below cover September 2026 unless otherwise stated.
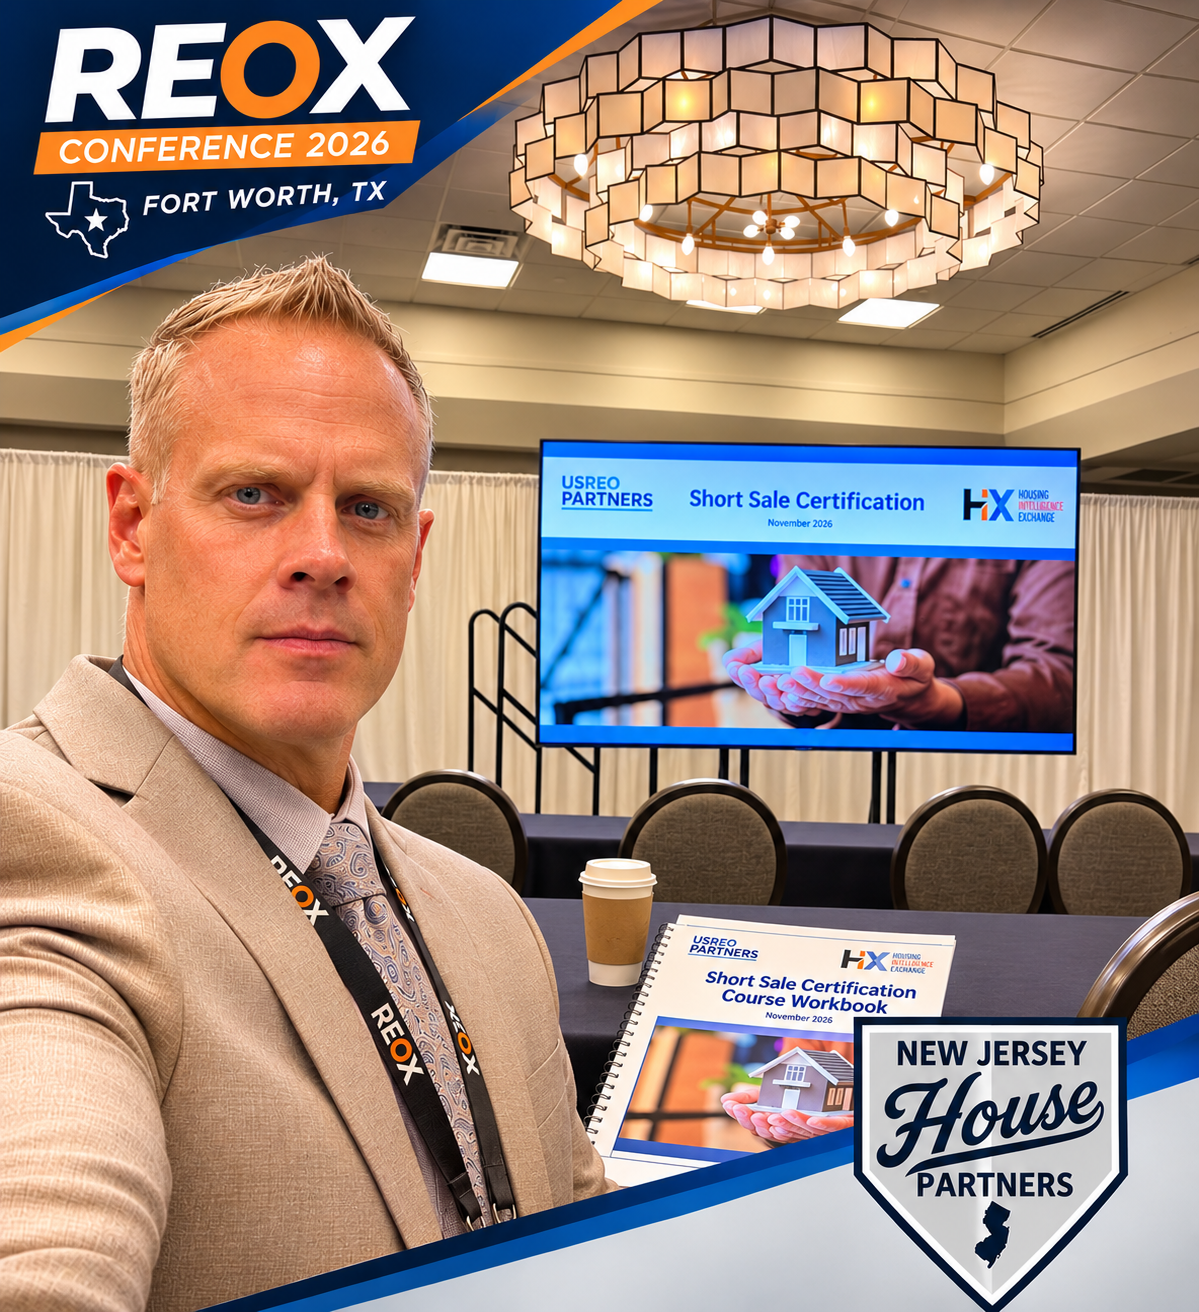
I returned from REOX at HIX2026 in Fort Worth, November 7 to 10, 2026, with my Short Sale Specialist Certification and a question: Are the pressures affecting other housing markets beginning to show up here?
Conversations with agents, mortgage servicers who handle loan payments, and asset managers who oversee properties for lenders and investors put my own listings in perspective. More competition among condos, homeowners exploring short sales and properties eventually becoming bank-owned can be different stages of the same pressure.
North Jersey is showing some early signals, especially among townhouses and condos. Understanding the sequence helps homeowners decide when to adjust their plans, before financial pressure narrows their choices.
The sequence I watched in 2008, and why it matters now
I was working as a residential appraiser during the housing bubble and the 2008 downturn. Across more than 20 years in real estate, including short sales, foreclosures and REO work, I have learned to watch how pressure builds before it becomes obvious in bank-owned listings.
The pattern I watch is straightforward: condos soften first, short sales can follow, and bank-owned inventory arrives much later. It is a useful framework for reading the market, rather than a fixed path every property or neighborhood follows.
North Jersey remains resilient. Nationally, September 2026 existing-home sales fell 2.2% year over year, inventory rose 4.6% and the median price increased 1.3% to $417,500. [1] Bergen County’s single-family market still had just 2.6 months of supply, with its median price up 1.2%. [2]
Stage 1: Condos are softening first
In my work, condos often show pressure before single-family homes. Buyers can compare similar units directly, and association dues, assessments (extra association charges), insurance and financing eligibility all affect what they can afford.
My Bergenfield condo listing remains on the market despite several price reductions. That experience keeps me focused on the competition and the buyer’s full monthly cost, because a lower asking price alone does not produce a signed contract.
The local reports show why this segment deserves attention. NJ REALTORS® combines townhouses and condos in these figures. [2] [3]
| Measure | Bergen County | Passaic County |
|---|---|---|
| Inventory change | +14.2% | +56.0% |
| Months of supply, 2025 → 2026 | 3.2 → 3.7 | 2.3 → 3.4 |
| Days on market until sale, 2025 → 2026 | 42 → 42 | 43 → 33 |
| September 2026 median sale price | $527,000 | $392,500 |
| Median price change | +5.6% | −8.9% |
| Percent of list price received, 2025 → 2026 | 100.7% → 99.6% | 102.7% → 101.4% |
Inventory increased in both counties, while sellers received a smaller percentage of asking price. That gives buyers more choice and sellers less room to overprice. Prices moved in different directions, and September selling times did not increase in either county.
The list-price measure excludes seller concessions, such as a credit toward the buyer’s costs. It is one piece of the picture alongside inventory, selling time and the terms needed to get a deal closed.
This is where I see the clearest early signal: growing competition among townhouses and condos, while single-family prices are still holding. A condo owner should review comparable units available now, showing feedback and association questions before deciding another price reduction will solve everything.
Stage 2: Short sales come next
A short sale happens when a home’s sale proceeds will not cover the mortgage debt and the lender agrees to accept less than the full payoff so the sale can proceed. The homeowner still owns the property. “Short” describes the money available, not a quick closing. [4]
Suppose you owe $500,000, but the best realistic sale price is $450,000. Selling expenses reduce what is available to the lender even further. A short sale requires approval, including agreement from additional mortgage holders where applicable; the unpaid balance is not automatically forgiven. [4]
This can put a distressed property on the market while its owner still has a chance to resolve the debt through a sale, years before it might otherwise become bank-owned. That is why I wanted to keep my short-sale training current.
Financial trouble does not automatically mean a short sale. Someone struggling with monthly payments may still have enough equity, the value beyond what they owe, to sell, pay off mortgages and other liens, cover selling expenses and keep money. I start by comparing realistic value with estimated net proceeds. [5]
That is why being house rich but cash poor deserves attention early. Knowing what you could keep from a sale helps you weigh your options before missed payments create more urgent decisions.
A short-sale listing I handled in Pompton Lakes a few years ago fell through because not all of the sellers were fully on board and doing their part. That experience reinforced an essential lesson: a short sale has little chance of approval unless every seller cooperates. All sellers need to supply the required financial paperwork, respond promptly, cooperate with showings and work with their attorney and lender.
I can market the property and help keep the process moving, but I cannot provide a homeowner’s records or make decisions for them. Before proceeding, have an attorney review any remaining debt and the approval terms. Pursuing a short sale does not automatically stop foreclosure proceedings. [4] [5]
Stage 3: REO lags years behind
REO means “real estate owned,” the industry term for property a lender owns after foreclosure. At the conference, an asset manager explained that financial trouble beginning now might not produce a bank-owned listing until around 2030 in a prolonged New Jersey case.
That is a possible delay, not a standard four-year schedule or a prediction of a 2030 wave. New Jersey uses a court foreclosure process, with separate steps between missed payments, a foreclosure complaint, a sheriff’s sale and a property becoming available to buyers. [6]
Settlements, adjournments and bankruptcy proceedings can postpone, cancel or reschedule a sheriff’s sale. [7] From my REO work, possession, title issues and property preparation can also delay a listing after ownership changes. A home bought by a third party at auction never becomes lender-owned inventory.
Another asset manager reported more pronounced foreclosure activity on the New Jersey side of the Philadelphia market than in North Jersey. ATTOM’s August 2026 report identified Salem, Cumberland, Camden and Gloucester as the state’s counties with the highest foreclosure filing rates. [8]
Understanding New Jersey foreclosure risk means recognizing that today’s bank-owned inventory can reflect yesterday’s financial trouble. A possible long process is no reason to wait for help, because individual deadlines still matter and some cases move faster.
I also attended Bob Norrell’s “Becoming an Asset Manager’s Dream” workshop, which addressed common REO pitfalls and what asset managers expect from the agents representing them. [9]
What I’d tell a North Jersey homeowner right now
I see early pressure in the townhouse-condo numbers and in my own listings, alongside a single-family market that remains firmer. We do not need to wait for a surge of bank-owned homes to make sensible decisions about pricing, equity and timing.
For a family handling an inherited home, the questions are similar: what is it worth, what does it cost to hold, and what would a sale leave after expenses? My guide to decisions executors should not rush addresses the broader planning issues.
- Price against current competition. Review recent closings alongside the properties buyers can choose today. A strong sale from earlier in the year is useful evidence, not a promise.
- Prepare condo information early. Find out what buyers and lenders will need about the association, its finances, insurance and any assessments. Address questions before they threaten a transaction.
- Compare the money you keep. Weigh likely sale proceeds against preparation costs, concessions, carrying costs and timing.
- Get help early if payments are becoming difficult. Contact your mortgage servicer, review your equity and seek qualified legal advice about deadlines. NJHMFA offers free foreclosure-prevention counseling for eligible homeowners. [10]
Start with your NJ Home Equity Checkup
If you are considering selling, own a condo that is taking longer than expected to move, are managing an inherited home or are feeling squeezed by monthly costs, let’s put actual numbers around your options.
My complimentary NJ Home Equity Checkup is a confidential, no-obligation review of your estimated market value, equity and potential net sale proceeds. We can compare a traditional listing, selling as-is and a direct cash offer where appropriate.
Request your NJ Home Equity Checkup or call 201-214-1349.
Your Home. Your Equity. Your Options.
Kevin Hill, REALTOR® | Keller Williams Valley Realty | NJ House Partners. The checkup is a real estate market analysis, not a formal appraisal. This article provides general information; consult your attorney, tax adviser and mortgage servicer about your circumstances.
Sources and reporting notes
Conference conversations are paraphrased firsthand recollections. County medians reflect the mix of sales; individual properties vary. ATTOM’s filing-rate rankings do not establish which region’s activity is growing fastest. Statistics retain their original reporting periods. Sources checked November 11, 2026.
- NAR, September 2026 existing-home sales.
- NJ REALTORS®, Bergen County, September 2026.
- NJ REALTORS®, Passaic County, September 2026.
- CFPB, What is a short sale?
- CFPB, Avoid foreclosure.
- Morris County Sheriff, About Sheriff’s Sales.
- Bergen County Sheriff, About Foreclosures & Sales.
- ATTOM, August 2026 foreclosure filing rates.
- Housing Intelligence Exchange, 2026 conference agenda.
- NJHMFA, Foreclosure Prevention Counseling.